Federal financial investigators provisionally attach properties valued at ₹129.85 crore across three dairy processors accused of laundering illicit profits from spurious temple supplies.
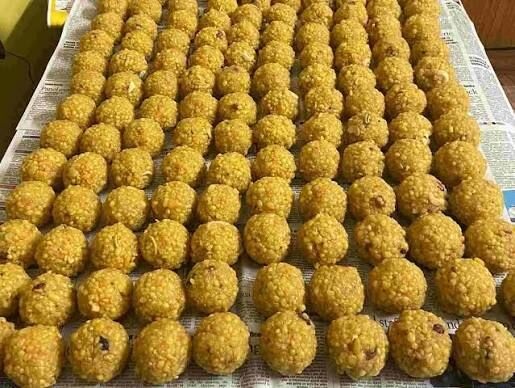
The Enforcement Directorate has provisionally attached immovable and movable properties valued at ₹129.85 crore under the Prevention of Money Laundering Act in connection with a multi-state investigation into the commercial supply of adulterated ghee to the Tirumala Tirupati Devasthanams. Initiated on the basis of a criminal First Information Report registered at the Tirupati East Police Station, the federal attachment orders target assets owned by Bhole Baba Organic Dairymilk Private Limited, Sri Vyshnavi Dairy Specialities Private Limited, and Sukriti Foods Private Limited, alongside corporate promoters Vipin Jain, Pomil Jain, Kailash Chand Mangla, and associated family entities. Combining these latest provisional attachment orders with previous seizures and bank account freezes executed under Section 17 of the money laundering statute brings the cumulative value of confiscated assets in the investigation to ₹132.55 crore. The regulatory enforcement represents one of the largest financial crackdowns on commercial dairy adulteration and corporate procurement fraud in the history of the Indian dairy commodities sector.
From an industrial processing and biochemical perspective, forensic laboratory analysis revealed that the accused dairy enterprises systematically manufactured artificial ghee formulations designed to mimic genuine bovine milk fat while avoiding standard sensory detection. Investigators established that the processing units blended commercial consignments of refined palm oil, palm kernel oil, and imported palmolein with chemical additives, including mono- and diglycerides, acetic acid esters, lactic acid, and beta-carotene to simulate the characteristic golden hue, crystallization grain, and aroma of pure cow ghee. These processed vegetable fat blends were then billed through accounting registries under misleading edible oil designations before being packaged and delivered into institutional tender pipelines. By replacing cost-intensive milk fat solids with cheap tropical oils, the manufacturing entities achieved massive gross margins while circumventing standard basic purity tests previously utilized at institutional receiving docks.
In terms of market procurement mechanics and tender competition, the criminal network established a web of front companies and intermediary shell distributors to capture institutional ghee supply contracts. Accused promoters orchestrated paper transactions that generated fictitious raw milk and butter purchases across regional procurement centers, routing commercial payments through formal banking channels before extracting the liquidity in cash via hawala networks. These unrecorded cash reserves were subsequently deployed to finance shell purchasing entities, pay commissions to intermediary suppliers, and fund illicit trading operations across northern and southern milksheds. This artificial cost structure allowed the cartel to submit aggressively low institutional tender bids, systematically undercutting legitimate cooperative dairy federations and private processors whose quotations reflected genuine farmgate milk procurement and butter conversion costs.
From a balance sheet and regulatory risk perspective, the widespread attachment of processing facilities, land holdings, and commercial bank accounts eliminates corporate liquidity for the implicated dairy enterprises. Enforcing asset attachments under anti-money laundering legislation marks a strategic shift in regulatory oversight, transitioning dairy food safety violations from minor municipal food safety penalties into severe financial predicate offenses carrying permanent asset forfeiture. Commercial banks and non-banking financial companies extending working capital credit lines to agro-industrial processors are now facing heightened collateral risks and debt impairment liabilities tied to compromised borrower balance sheets. Furthermore, institutional purchasers across India are overhauling enterprise risk management frameworks, mandating verified third-party laboratory audits and continuous vendor provenance certifications before disbursing contract advances.
At the farmgate level, stamping out synthetic ghee substitution is essential to restoring fair market clearing prices for authentic milk fat and protecting smallholder dairy incomes. When illicit commercial suppliers flood institutional markets with palm-based dairy imitations, downstream demand for liquid raw milk softens, directly depressing fat-based procurement payouts distributed to village dairy cooperative members. As premier temple trusts and state federations transition to mandatory gas chromatography and foreign fat testing under ISO 17678 standards, procurement systems are eliminating low-cost synthetic adulterants from national supply chains. Heading into 2027, sustained law enforcement coordination between anti-money laundering authorities, the Central Bureau of Investigation, and state dairy regulators will remain critical to deterring corporate food fraud, maintaining institutional tender integrity, and securing remunerative farmgate returns for genuine dairy producers.
Source: NewsMeter
You can now read the most important #news on #eDairyNews #Whatsapp channels!!!
🇮🇳 eDairy News ÍNDIA: https://whatsapp.com/channel/0029VaPidCcGpLHImBQk6x1F